What is the scope and industry significance of the Satellite Imagery Market?
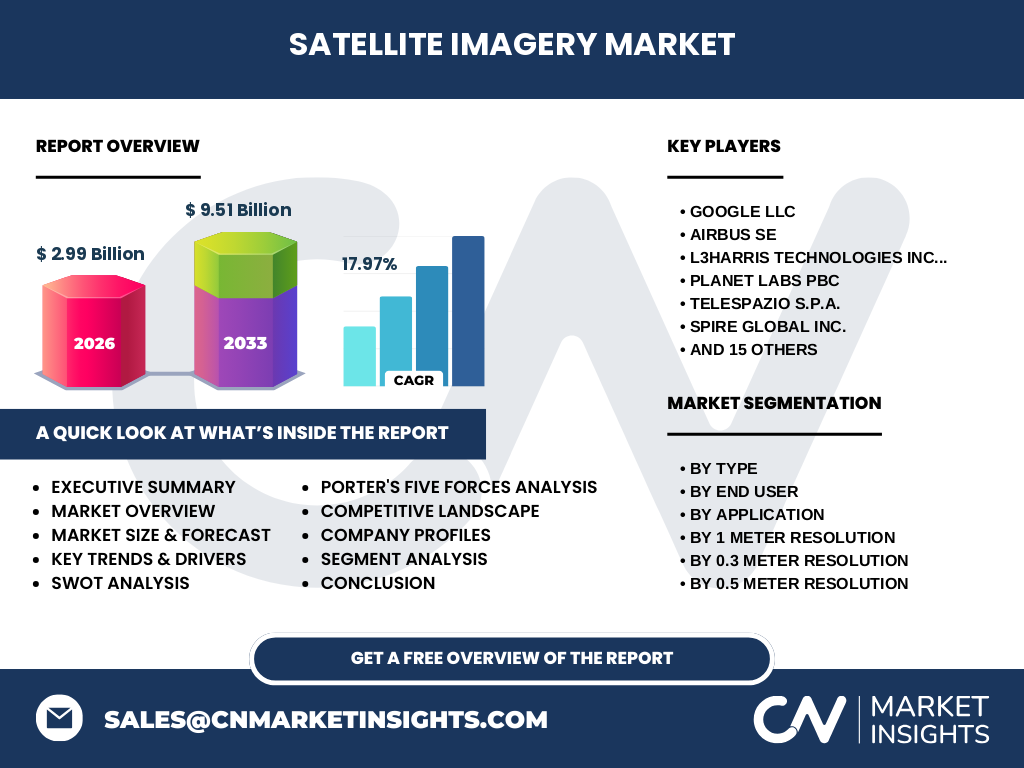
Our analysis indicates that the Satellite Imagery Market achieves a valuation of 2.99 Billion in 2026, driven by high-resolution Earth observation. This sector underpins global geospatial intelligence, enabling defense agencies and commercial enterprises to monitor infrastructure, track climate change, and optimize supply chains with unprecedented spatial accuracy.
What are the primary market drivers, restraints, challenges, and opportunities shaping the Satellite Imagery Market?
The market is propelled by surging demand for real-time intelligence and plummeting launch costs, though regulatory friction from bodies like the NOAA remains a restraint. Key opportunities lie in integrating AI analytics with constellations operated by Planet Labs PBC and BlackSky Technology Inc. to automate change detection for commercial clients.
Emerging trends and growth patterns in the Satellite Imagery Market
The industry is shifting rapidly toward Synthetic Aperture Radar (SAR) constellations, championed by innovators like ICEYE Oy and Capella Space Corp., which bypass cloud cover limitations. This technical shift alters growth patterns by unlocking persistent day-and-night monitoring capabilities critical for maritime tracking and disaster response.
How did COVID-19 impact the Satellite Imagery Market and shape its recovery trajectory?
During the pandemic, the Satellite Imagery Market experienced temporary supply chain bottlenecks in satellite manufacturing and delayed government procurement cycles. However, the crisis accelerated digital transformation, boosting demand for remote monitoring solutions by enterprises seeking to manage operations without on-site personnel.
Competitive benchmarking and strategic dynamics in the Satellite Imagery Market
Market concentration features a mix of defense primes like L3Harris Technologies Inc. and agile NewSpace entrants like Spire Global Inc. Strategic dynamics revolve around vertical integration, where firms acquire analytics startups to transition from raw imagery providers into comprehensive geospatial insight platforms.
Executive summary of key findings for the Satellite Imagery Market
Our comprehensive research reveals a projected market expansion to 9.51 Billion by 2033, expanding at a robust 17.97% CAGR from 2027. This acceleration is heavily anchored in surging defense surveillance requirements and the commercial adoption of smart city analytics across urban centers.
Satellite Imagery Market forecast and projected growth from 2027 to 2033
Based on our econometric modeling, the Satellite Imagery Market will scale dramatically from its 2026 baseline of 2.99 Billion to reach 9.51 Billion by 2033. Achieving a 17.97% CAGR, this trajectory reflects compounding demand for high-frequency, sub-meter optical and radar data streams.
Segmentation analysis across types, end users, and applications
Segmentation divides the Satellite Imagery Market by resolution (0.3M, 0.5M, 1M), end users (Government, Defense), and applications (Geospatial Data Acquisition, Navigation And Mapping). 0.3 Meter Resolution dominates critical infrastructure monitoring, while 1 Meter Resolution powers large-scale environmental studies and weather observation.
Geographic distribution and regional performance in the Satellite Imagery Market
Regional performance highlights North America as the dominant revenue generator due to extensive defense budgets and established commercial players. Meanwhile, the Asia-Pacific region demonstrates the fastest growth rate, fueled by localized investments in indigenous earth observation constellations by nations like China and India.
In-depth regional review of the Satellite Imagery Market
North America maintains leadership in the Satellite Imagery Market, supported by robust procurement from agencies like the NGA and commercial dominance by firms such as Maxar (via partnerships). Europe follows closely, driven by Copernicus program data distribution and specialized European providers like Telespazio S.p.A.
Strategic positioning of leading companies in the Satellite Imagery Market
Industry leaders like Google LLC leverage vast cloud computing infrastructure to process petabytes of earth data, while specialized operators like Satellogic Inc. and Umbra Lab Inc. focus on high-revisit, low-cost constellations. Airbus SE maintains a formidable defense foothold through its tasking of sovereign optical satellites.
Porter's Five Forces analysis of the Satellite Imagery Market
Bargaining power of suppliers is moderate, constrained by specialized launch vehicle availability. Threat of new entrants is mitigated by high capital expenditure requirements for satellite deployment, though venture funding for SAR innovators like Synspective Inc. continues to test traditional competitive moats.
SWOT analysis of the Satellite Imagery Market
Strengths include unmatched global coverage and high spatial fidelity. Weaknesses involve high orbital debris risks and spectrum allocation bottlenecks. Opportunities abound in precision agriculture and carbon offset verification, while threats stem from geopolitical tensions affecting orbital assets and international trade compliance.
Value chain analysis from raw materials to end-users
The value chain originates with raw material procurement for sensors and bus manufacturing, flowing through launch services and ground station downlinks. Midstream processing transforms raw pixels into analytics, delivering actionable intelligence to end-users like defense ministries, urban planners, and agricultural cooperatives.
Investment insights and high-potential areas in the Satellite Imagery Market
High-potential investment targets include AI-driven automated feature extraction and SAR technology providers. Investors should focus on companies addressing high-frequency monitoring niches, as enterprise clients increasingly demand predictive analytics rather than static historical imagery archives.
Conclusion and key takeaways for stakeholders
The Satellite Imagery Market represents a high-growth frontier transitioning from niche defense utility to ubiquitous commercial infrastructure. With a clear path to 9.51 Billion by 2033, stakeholders must prioritize software integration and rapid data delivery to capture market share.
Research methodology used to evaluate the Satellite Imagery Market
Our baseline estimates are rigorously triangulated by combining trade registry data, primary stakeholder interviews with aerospace executives, and secondary macroeconomic indicators. This multi-layered approach ensures precise sizing of the Satellite Imagery Market size across all designated segments.
Scope of the report and coverage parameters
This research report covers global trends within the Satellite Imagery Market industry trends, analyzing commercial and defense applications from 2026 through 2033. Limitations include excluding unverified micro-constellation ventures and focusing strictly on operational commercial imagery providers.
Recent developments, partnerships, and strategic moves in the market
Recent milestones include HawkEye 360 expanding its RF monitoring constellation and Spire Global Inc. securing major maritime tracking contracts. These moves demonstrate a clear industry shift toward specialized radio frequency and multi-sensor data fusion to outpace traditional optical limitations.